
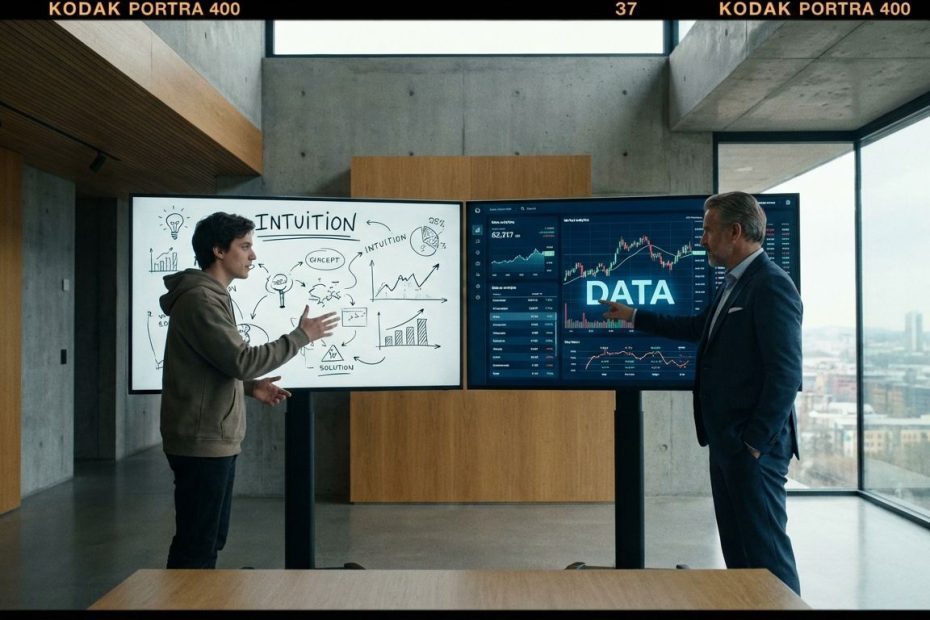
High-stakes strategy demands highly repeatable mathematical validation in liquid capital markets, whereas technology founders building early-stage companies must lean heavily on qualitative human pattern recognition before definitive product-market fit materializes. You will master the exact operational risk balances top portfolio managers and rapid-growth commercial operators use to deploy venture capital and engineering resources highly efficiently. You will walk away from this material knowing exactly when to strictly trust quantitative analytics dashboards and exactly when to override algorithmic outputs with raw executive judgment.
Should Hedge Funds Rely More On Data Or Manager Intuition?
Top tier systematic hedge funds strictly mandate highly rigid quantitative measurement as the absolute foundational baseline for deploying massive institutional capital allocations safely. Systematic mathematical algorithms provide exact operational repeatability, strictly enforced programmatic risk constraints, and constant real-time signal evaluation across thousands of uncorrelated global market variables. Relying entirely on a discretionary portfolio manager’s unsupported gut feeling exposes the financial institution to massive emotional behavioral biases and completely unmanaged capital drawdowns during sudden macroeconomic shocks. You must build highly sophisticated electronic execution systems that remove human hesitation from daily trading operations entirely to capture fleeting statistical arbitrages before competitors react.
You utilize raw human intuition specifically for framing original non-obvious market hypotheses, defining firm-wide mathematical risk parameters, and overriding obvious algorithmic failures during black swan events. Discretionary human judgment shines brightest during completely unprecedented macroeconomic regime shifts where historical statistical backtests offer zero mathematical predictive value. Human operational experience dictates the exact boundaries of the financial playing field, setting the strict programmatic rules that algorithmic execution models process flawlessly at microsecond speeds. The highest performing global portfolio managers combine deep fundamental domain expertise with rigid quantitative position sizing rules to protect client capital aggressively.
Systematic statistical arbitrage funds continuously backtest historical datasets and monitor live execution signals to strip away human behavioral errors from the trading layer entirely. Discretionary fundamental funds rely heavily on seasoned human pattern recognition to evaluate unquantifiable variables including executive management quality, hidden competitive business moats, or sudden geopolitical legislative shifts. You merge these two distinct operational disciplines by building strict quantitative execution guardrails around highly qualitative, deeply researched fundamental investment theses. Institutional capital allocators increasingly demand this exact hybrid operational methodology to ensure massive financial returns remain highly repeatable and structurally defensible.
Why Do Hedge Funds Need Data-Driven Decisions More Than Startups Do?
Global capital markets generate continuous, extremely high-volume statistical price feedback wrapped in an adversarial environment designed specifically to destroy poorly managed capital. Small mathematical execution edges combined with aggressive programmatic risk control determine mathematically whether a proprietary trading firm survives the quarter or liquidates entirely. Quantitative researchers utilize massive cloud-based data pipelines to perform daily algorithmic signal attribution, granular factor exposure analysis, and ruthless mathematical drawdown diagnostics. You must instrument heavy systematic position sizing algorithms for highly liquid public markets to defend your specific statistical edge against highly sophisticated competing algorithms.
Technology founders operate in incredibly low-signal commercial environments where waiting for absolute statistical significance practically guarantees running out of venture capital completely. Pre-product-market fit software companies deal with mathematically insignificant sample sizes, highly unstable enterprise marketing funnels, and poorly defined ideal customer demographic profiles. Trusting immature internal operational dashboards over direct human-to-human customer conversations creates a highly dangerous illusion of business certainty that delays critical product pivots. You must prioritize high-velocity qualitative customer discovery calls over deep analytical spreadsheet modeling during the earliest stages of software company building.
Quantitative trading operations optimize entirely known mathematical variables to extract fractional percentages of alpha from highly efficient electronic public markets. Venture-backed startup teams search relentlessly for completely unknown commercial variables to build entirely new software markets from absolute scratch. Public market electronic traders possess millions of daily microscopic data points to validate their specific statistical trading thesis mathematically within seconds. Early-stage technology founders must rely heavily on qualitative human signals, deep psychological consumer profiling, and raw commercial market pull to validate their initial business hypotheses.
How Can Startups Avoid Analysis Paralysis While Still Being Data-Driven?
You build an elite analytical engineering culture around making highly specific business decisions rather than endlessly accumulating raw operational database metrics. Strong commercial operators work backward from the precise strategic business choice they need to execute, asking what exact numerical evidence alters their planned engineering roadmap. Ignoring superficial vanity metrics and curiosity-driven database queries prevents highly paid engineering teams from confusing rapid technical motion with actual commercial revenue progress. You must demand strict financial return-on-investment calculations for every single engineering hour spent building internal operational data visualization dashboards.
Rapidly scaling software technology companies instrument newly developed features using modern product analytics platforms and ship code updates behind tightly controlled deployment feature flags. Software engineering teams run highly structured statistical tests on meaningful user experience alterations to validate commercial conversion rate improvements mathematically. They simultaneously reserve highly qualitative executive judgment calls concerning complex enterprise sales motions and core brand positioning for direct founder-to-customer verbal feedback loops. This highly aggressive dual-track operating model ensures your business moves extremely fast without flying completely blind into highly competitive new enterprise software markets.
A highly effective corporate operating structure treats quantitative statistical measurement and qualitative human discovery as entirely separate, highly optimized professional workflows. You rely on modern cloud-based data warehouses and basic data visualization tools to track core product retention metrics systematically across thousands of active users. You conduct direct human user interviews daily to understand the deep psychological consumer motivations driving the specific numerical outputs on the analytics screen. Building this strict operational reporting cadence prevents highly technical product teams from drowning in endless analytical feedback loops that permanently stall new software delivery.
What Do High-Stakes Decisions Look Like In A Hedge Fund Versus A Startup?
Institutional portfolio managers make continuous mathematical risk allocation choices under massive uncertainty with immediate, highly visible financial profit and loss consequences. They dictate exact gross and net global market exposures, cap highly specific statistical factor concentrations, and execute immediate mathematical hedges during sudden volatility spikes. Managing technical operational governance determines exactly when to trust a complex deep learning signal lacking complete human interpretability but generating massive alpha. You must deploy strictly enforced quantitative risk limits for every active trading strategy to prevent catastrophic institutional capital destruction during sudden flash crashes.
Early-stage technology founders make massive directional strategic bets regarding core product architecture, global go-to-market distribution, and target enterprise audience that require months to validate mathematically. Choosing to aggressively scale an expensive outbound sales team before proving highly repeatable commercial unit economics represents a massive, completely fatal operational error. Aggressive corporate hiring based on early venture capital press coverage rather than highly stable user retention metrics drains cash reserves rapidly and destroys raw equity value. You must maintain highly conservative corporate cash burn rates until pure commercial market demand literally rips the software product out of your hands.
The precise financial cost of a human execution error in highly liquid capital markets registers on the institutional balance sheet within milliseconds. This incredibly rapid financial feedback loop demands fully automated mathematical stop-loss orders and highly precise algorithmic execution systems operating at microsecond latencies. The true financial cost of building the wrong enterprise software feature remains completely hidden from management until the venture capital funding runway vanishes entirely. You must implement ruthless external customer validation cycles for all internal product roadmaps to mitigate this massive structural commercial blindness.
Are Quant Funds Taking Over Discretionary Hedge Funds Entirely?
Systematic mathematical algorithms and discretionary human trading models continue to coexist alongside an aggressively accelerating trend toward highly hybrid, data-assisted investing styles. Pure fundamental research shops increasingly integrate obscure alternative data feeds, anonymized credit card scraping operations, and global satellite imagery to augment traditional financial spreadsheet modeling. The absolute boundary between raw human judgment and purely automated machine execution shifts consistently toward highly collaborative quantitative systems. You maximize total institutional alpha generation by heavily arming deeply experienced fundamental financial analysts with massive computational engineering resources.
Quantitative mathematical execution strategies excel at extracting massive profits from highly compressed short time horizons, statistical pair arbitrage, and highly repeatable market micro-structures. Discretionary fundamental portfolio managers retain a massive structural financial advantage in highly sparse-data situations, idiosyncratic corporate restructuring events, and complex activist proxy campaigns. Experienced human traders navigate completely unprecedented macroeconomic policy shocks far better than highly rigid deep learning algorithms trained strictly on historical price distributions. You deploy pure systematic algorithmic capital for highly liquid global asset classes and strictly reserve human operational discretion for distressed corporate debt.
Large systematic global financial organizations maintain massive structural engineering advantages regarding elite engineering talent acquisition, massive cloud data pipelines, and proprietary execution technology. You build entirely dominant global financial institutions by heavily empowering deeply experienced human financial capital with absolute world-class computational engineering infrastructure. The most successful global mega-funds operate strictly in the highly complex middle ground, demanding extremely deep quantitative mathematical validation for every qualitative fundamental thesis. Pure discretionary fundamental funds actively refusing to adopt modern computational data science techniques face severe, completely irreversible institutional capital outflows.
Which Metrics Matter Most When Intuition Conflicts With Hard Data?
You resolve internal corporate operational conflicts by indexing strictly on fundamental survival constraints, heavily prioritizing absolute maximum drawdown limits in volatile public markets. Quantitative fund managers track risk-adjusted mathematical performance metrics, absolute volatility ceilings, and strict maximum drawdown thresholds to prevent purely automated pattern-mining blowups. Highly rigid mathematical execution boundaries prevent emotionally compromised portfolio managers from doubling down on catastrophic losing market positions based on pure personal conviction. Strict regulatory compliance filings and highly detailed industry-wide aggregate financial reporting demand institutional risk measurement as a core mandatory daily behavior.
Rapidly growing enterprise software companies track early product-market fit signals, prioritizing raw organic user retention, exact cohort activation rates, and highly explicit enterprise willingness to pay. Startup founders utilize strict quantitative diagnostic metrics to precisely measure monthly cash burn against actual sales funnel efficiency, preventing highly destructive premature scaling behaviors. Evaluating pure commercial market pull through hard booked revenue numbers instantly invalidates a highly optimistic, completely untested internal software product thesis. You must ruthlessly terminate massive digital marketing budgets when calculated customer acquisition costs mathematically exceed total projected customer lifetime value.
Conflicting internal operational data signals require your immediate decisive reversion to the single fundamental mathematical metric dictating your daily corporate survival. You liquidate quantitative market trading positions the exact millisecond the calculated value-at-risk exceeds the specific institutional mandate, entirely regardless of personal belief in the asset. You completely shut down entire software engineering product lines when specific thirty-day user retention metrics fall permanently below highly viable commercial thresholds. Hard quantitative operational data must always strictly override highly optimistic human assumptions when immediate corporate financial survival remains highly questionable.
What Is The Main Difference Between Hedge Fund And Startup Strategy?
- Hedge funds deploy exact mathematical risk models to optimize continuous, high-volume price feedback in completely liquid global public markets.
- Startup founders leverage highly qualitative human intuition to discover viable business models inside noisy, highly ambiguous, low-signal commercial environments.
- Institutional traders manage immediate fractional capital drawdowns, whereas enterprise operators strictly manage long-term corporate runway preservation.
Master The Art Of Decision Making Across Any Market Condition
You now possess the exact operational models required to navigate highly ambiguous startup environments and mathematically rigid electronic trading floors. Implement strict quantitative programmatic guardrails to protect your immediate downside financial risk while trusting raw executive instincts to uncover massive, non-obvious commercial opportunities. Measure your software retention rates and capital drawdowns obsessively to guarantee institutional survival during periods of high economic turbulence. Execute your strategic operational vision relentlessly, strictly blending deep mathematical quantitative validation with aggressively decisive action to outpace your global competition daily.
References
- Reddit Quant Finance Community Discussion
- Financial Times: Cliff Asness on Machine Learning in Funds
- Reddit SaaS: Scaling and Growth Rate Decisions
- Reddit Product Management: Bridging the Analytics Gap
- Reddit Startups: Instrumentation and Metrics
- Startup Genome: The Anatomy of Premature Scaling
- CB Insights: Top Reasons Why Startups Fail
- Reddit Hedge Funds: Systematic vs Discretionary Trading
- Reddit Quant: Starting Fundamental vs Systematic Funds